From digital adoption to intelligent execution: How operational excellence is reshaping financial services


Financial services is entering a phase where technology adoption alone is no longer enough. As customer expectations move towards instant, personalised and context-driven experiences, banks and financial institutions are increasingly relying on technology ecosystems to deliver decisions and services in real time.
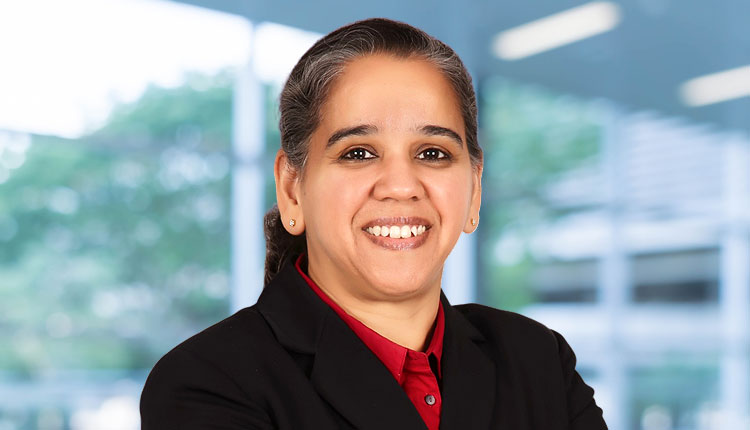
For Veena Rao, Chief Operating Officer at Perfios, the transformation is not happening within banks or technology companies in isolation. It is emerging from the intersection of the two.
“True transformation happens only when banks and the technology ecosystem come together as synergistic partners,” Rao says, pointing to a fundamental shift in the relationship between financial institutions and technology providers. Banks bring deep understanding of products, customers and services, while technology partners provide the specialised capabilities needed to deliver those experiences at scale.
The result is a reinforcing cycle. Customer expectations drive banks to adopt new technologies, while advances in technologies such as data analytics, fraud detection, APIs, large language models and agentic workflows raise the bar for what customers expect from financial services.
For the next generation of banking customers, seamless digital experiences have become the norm. Whether it is social media, e-commerce or entertainment, consumers are accustomed to services that are personalised, contextual and available precisely when and where they need them. Financial services increasingly face the same expectation.
A vehicle loan, for instance, is no longer simply a banking product. Customers increasingly expect it to be approved instantly, through their preferred channel, embedded within the purchase journey and tailored to their financial profile.
This is fundamentally changing the role of technology in financial services. Banks are increasingly becoming orchestrators of specialised technology ecosystems, while technology companies are moving beyond traditional vendor relationships to become deeply embedded partners in banking infrastructure.
Scaling technology without losing agility
For technology companies serving large financial institutions, however, growth brings a different challenge: how to scale without sacrificing the agility and innovation that fuelled the organisation’s early growth.
Rao believes that agility by itself is insufficient when serving tier-1 financial institutions. Global expansion requires institutional predictability — from security and compliance to availability, deployment timelines and service-level commitments.
The answer, she argues, lies in building the right operational “plumbing” behind the organisation. Well-designed processes should take care of recurring business-as-usual activities, allowing product, engineering, sales and customer-success teams to remain focused on innovation and customer needs.
At Perfios, this approach is built around three principles: centralised governance with localised execution, standardised playbooks, and guardrails rather than gatekeeping.
Core areas such as platform architecture, security, data privacy, quality assurance and roadmap governance can be managed centrally, while customer-facing execution, solutioning and co-innovation remain closer to local markets.
Standardised frameworks then make international expansion repeatable, while clearly defined boundaries around markets, solutions, pricing and ROI allow teams to move independently without losing organisational discipline.
The objective is not to create layers of bureaucracy. It is to make operations predictable enough that innovation can happen faster.
Operational excellence is ultimately about customer outcomes
For Rao, operational excellence cannot be reduced to conventional technology metrics such as uptime or release velocity.
In financial services, even a brief increase in latency at the wrong moment can have a direct customer impact — whether that means delaying an instant loan decision or disrupting a digital onboarding journey.
This makes operational excellence a combination of system resilience and measurable customer outcomes.
The first dimension is delivery precision: availability, API latency, predictable releases, security compliance and support response times. The second, and ultimately more important, dimension is business impact.
That includes reducing credit-processing turnaround times, increasing straight-through processing, improving funnel conversion, automating operational processes, enabling digital onboarding and strengthening fraud detection.
In other words, technology performance matters because of what it enables the business to achieve.
Moving AI from impressive pilots to production value
This distinction becomes particularly important as financial institutions accelerate their AI journeys.
The biggest challenge today, Rao argues, is not demonstrating what AI can do. It is moving successful proofs of concept from controlled environments into live, regulated banking workflows.
The complexity begins with data. Financial institutions deal with scanned documents, different bank-statement formats, complex financial statements and unstructured legal documentation. The quality and diversity of this data can make generic AI approaches difficult to deploy reliably in high-stakes decision-making.
Then comes the question of trust.
In lending and underwriting, AI cannot simply produce an answer; institutions need to understand why that answer was generated. Explainability, fairness, transparency, hallucination control and model governance become essential considerations.
There is also a business question around ROI. As AI technologies evolve rapidly, organisations still need clarity on productivity gains, cost savings and the economics of deploying AI at scale.
For Rao, this is where the next phase of enterprise AI will be determined: not by the number of pilots an organisation can run, but by its ability to demonstrate measurable outcomes in real-world environments.
Customer success as a strategic technology function
The same focus on measurable outcomes is reshaping the role of customer success.
Rao believes customer success sits at the point where technology products meet customer reality. When operations and customer success work closely together, customer-facing teams can become an important source of intelligence for product strategy.
At Perfios, this involves linking customer success to recurring revenue and customer satisfaction, while using structured customer interactions — including value-discovery workshops, roadmap discussions and senior stakeholder engagements — to capture strategic insights.
These insights can then feed into roadmap planning, sprint priorities and innovation initiatives.
This creates a feedback loop in which customers are not merely recipients of technology but participants in shaping how the product evolves.
The COO’s role is changing
As financial workflows become increasingly real-time and autonomous, the role of the COO is also expanding.
The modern COO must look beyond process efficiency and take an active role in governing the risks introduced by AI. That includes model governance, explainability, fairness, trust and model drift, as well as questions around data residency, privacy and security.
There is also a financial dimension. Organisations will need stronger frameworks for evaluating the risk-return equation of AI-led initiatives, making the COO increasingly central to conversations that span technology, operations, compliance and financial performance.
Ultimately, Rao sees the future of technology-led financial services resting on three interconnected pillars: innovation agility, trust with transparency, and always-on resilient service.
The message is clear. The next chapter of financial-services transformation will not be defined simply by who adopts the newest technology first. It will be defined by who can operationalise that technology responsibly, reliably and at scale — while delivering a better experience and measurable value to the customer.
For financial institutions and their technology partners, that means the real competitive advantage may increasingly lie not in technology alone, but in the operating model built around it.
