AI agents in lending: Why banks must govern decisions, not just automate workflows


For banks and non-banking financial companies (NBFCs), the next frontier of artificial intelligence is not how quickly a loan application can be processed, but how much decision-making authority an AI agent can safely exercise. As lending institutions experiment with increasingly autonomous systems, the challenge is shifting from automating predefined workflows to governing systems that can determine how to achieve an objective.
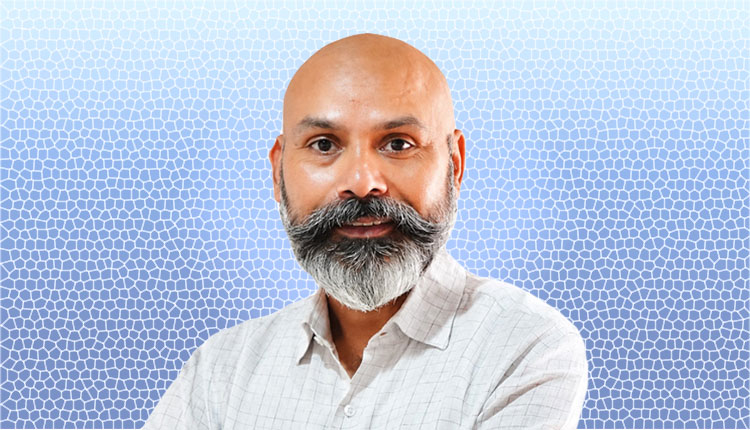
For Vineet Tyagi, Managing Director – India and Global Chief Product and Technology Officer, Biz2X & Biz2Credit, this distinction will determine whether AI moves from promising pilots to dependable lending infrastructure. His central argument is that agents can be autonomous in reasoning, but their authority to act must remain bounded by clear controls.
“Human should be on the loop, not in the loop,” Tyagi says, drawing a distinction between human intervention at every step and human oversight over how an autonomous system operates.
The distinction has significant implications for credit underwriting, where a seemingly routine decision can affect a customer’s access to capital, a lender’s risk exposure and its regulatory obligations.
From automating workflows to governing objectives
Traditional automation follows a predefined sequence: complete KYC, verify documents, assess eligibility and move the application to the next stage. AI agents operate differently. Given an objective, they can determine the sequence of actions needed to achieve it.
That flexibility makes them useful in document-heavy underwriting workflows. Agents can collate information, examine records and prepare insights, allowing underwriters to make informed decisions faster. Rather than eliminating the underwriter, the technology can reduce the operational work that consumes time before a credit decision is made.
However, the same flexibility makes agentic AI fundamentally different from conventional process automation.
“Automation is about a human workflow, a human-designed workflow,” Tyagi explains. “When you are creating agents, agents are given an objective they have to meet.”
An agent tasked with completing a credit assessment might identify missing information and request additional bank statements without waiting for a human to initiate each step. That does not mean it should have the authority to approve an exception to a lender’s credit policy.
Tyagi’s approach is to determine autonomy at the level of individual actions, rather than treating an entire process as either autonomous or human-controlled.
He evaluates potential actions against three parameters: reversibility, consequence and blast radius, the extent of damage an action could cause if it goes wrong.
Requesting additional documents is relatively reversible and carries limited downside. Approving a policy exception or making a consequential credit decision demands a different level of control.
For technology leaders, this suggests a more granular approach to AI deployment: establish permissions for what an agent can do, define where human authority is mandatory, and assess the potential impact of each action before granting autonomy.
Why a successful pilot is not production-ready
The pressure to demonstrate AI-led efficiencies can make successful pilots appear closer to deployment readiness than they really are.
Tyagi cautions against this assumption. “One per cent error rate in a pilot makes it look successful. But if you have one per cent error rate in production, that’s actually a very bad experience for some customers.”
At scale, errors are not merely technical exceptions. They can translate into inconsistent credit outcomes, customer friction and operational or compliance exposure.
For Tyagi, governance, particularly the ability to explain an agent’s actions is a more significant obstacle to scaling AI than infrastructure or policy alone.
A lender needs to understand why an agent reached a conclusion, which information it considered and how its reasoning aligns with the institution’s decision-making requirements. Explainability is therefore not simply a reporting feature added after deployment; it is part of the trust architecture required to put AI into production.
Bias presents another challenge. Models can reproduce patterns embedded in training data, even when developers have not deliberately introduced discriminatory outcomes. Tyagi advocates training on broader datasets, actively testing for bias and monitoring decisions in production.
His prescription is to establish explainability and auditability during pilots, examine actual decisions and their rationale, and only then expand the system’s autonomy.
For CIOs, CTOs and chief risk officers, this changes the question from whether an AI model performs well in a controlled test to whether its behaviour remains observable, defensible and sufficiently consistent under real-world operating conditions.
India’s digital infrastructure changes the lending equation
AI adoption is accelerating across India, the US and the Middle East, but Tyagi sees differences in where lending institutions are applying the technology.
In India, digital public infrastructure and the broader India Stack ecosystem create opportunities for customer onboarding, interaction and data-enabled decision-making. With appropriate consent, financial data accessed through mechanisms such as account aggregators can also support credit assessment.
Tyagi sees more customer-facing applications emerging in India, while deployments in the US and UAE place greater emphasis on regulatory considerations.
The distinction is not that one market is necessarily ahead of another, but that each market’s digital infrastructure and regulatory environment shape how AI is applied.
This has implications for Indian fintech product development. Technology built in India can serve financial institutions across markets, but international deployment requires products to accommodate different regulatory expectations, data environments and operating models rather than assuming that a successful domestic implementation can be replicated unchanged.
The next lending platform may be defined by its decision-making layer
Biz2X has previously announced an investment of ₹100 crore in AI initiatives, with Tyagi identifying model development for underwriting among the areas receiving attention. The company is also exploring conversational AI for customer engagement.
Looking ahead, Tyagi expects a substantial proportion of lending decisions to become automated. He anticipates that 50%–80% of decisions could eventually be made automatically, creating the possibility of near-real-time loan application, decision and disbursement experiences. This is an expectation, not a claim that the industry has already reached that level of automation.
For lending technology leaders, the larger question is what this means for traditional loan origination and lending management systems. As AI agents take on more operational tasks and decision-support functions, the value of lending infrastructure may increasingly depend on its ability to coordinate agents, govern their permissions, maintain audit trails and connect decisions to existing systems.
The future is unlikely to be a wholesale replacement of lending platforms by autonomous agents. It is more likely to involve a shift in where intelligence sits within the architecture — from rigid, sequential workflows towards systems that can interpret objectives while operating within institutional controls.
The competitive advantage will not come simply from deploying more agents. It will come from deciding precisely where they can act, proving why their decisions are defensible and ensuring that their autonomy does not exceed the consequences an institution is prepared to accept.
