Why Canara HSBC Life is rethinking its operating model around AI

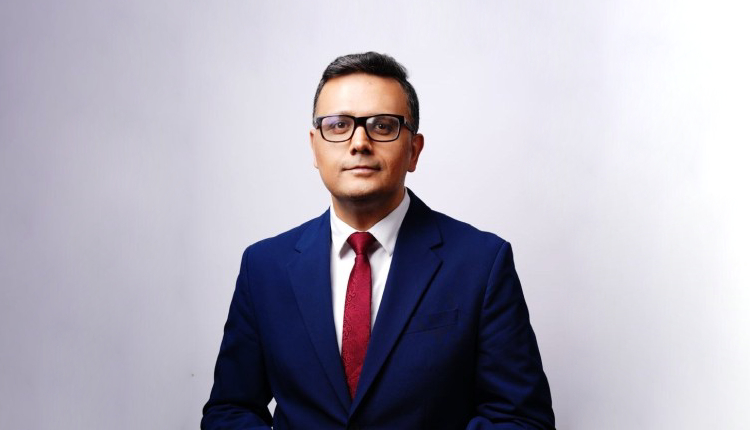

When Sachin Dutta, Chief Operating Officer of Canara HSBC Life Insurance, last discussed artificial intelligence with Express Computer in 2024, the conversation revolved around what generative AI might do for insurers. Two years on, that framing already feels dated to him.
“Right now, we don’t even talk much about Gen AI,” Dutta says, describing how the company’s AI journey has moved from experimentation towards more purposeful applications.
For Dutta, the shift is not about following the latest technology cycle. It is about having the architecture, data and operating foundations to make AI useful at scale. The company’s approach, he says, has been deliberately conscious and cautious, with business outcomes determining where AI is applied rather than the technology itself becoming the objective.
From experiment to an underwriting co-pilot
The change is visible in underwriting, where Canara HSBC Life has deployed what Dutta describes as a copilot or autopilot embedded into the workflow.
The system is intended to reduce turnaround time for underwriters and free them to spend more time on complex cases, while allowing some underwriting activity to be handled through the technology. “It also gives more green time to our team of underwriters who can now devote more time on complex cases and allow for some of the underwriting to be done by autopilot and co-pilot,” he says.
The deployment also illustrates the limits Dutta currently places around autonomy. The system does not operate without oversight. “There is always this human in the loop reviewing some of these cases so that the decision doesn’t go wrong,” he says. That balance between automation and human judgement is central to his view of how AI should evolve within an insurer.
Redefining what counts as return
Dutta’s definition of AI return on investment is broader than technology expenditure measured against immediate cost savings. Customer experience is an important part of the equation. “The discussion about ROI on AI is always more about how you do kind of save some money. I think it is not just about saving money,” he says.
For him, the other side of the equation is the value created through a better customer experience. A simpler process, a faster underwriting decision or clarity upfront about requirements can make an interaction more transparent and predictable. “If the process gets simpler for the customer, then that allows us to be more transparent and trustworthy as an organisation,” Dutta says.
He therefore sees turnaround time, predictability and the ability to settle genuine claims faster as part of the return from AI. The investment calculation also has to account for the less visible foundations required to make AI work, including data, data governance, risk and security.
The real work begins with legacy
The more difficult question for insurers may not be the AI model itself, but the environment into which it has to be introduced. Dutta identifies data readiness, integration with existing systems, change management, governance and security as critical elements of AI readiness. For insurers with years of accumulated systems and data, the challenge is particularly visible. “AI is a new technology and what you are dealing with is a legacy setup also,” he says.
Trying to integrate the two exposes how legacy data and systems have been structured over time. Dutta does not see that only as a cost or constraint. He argues that AI can also force organisations to confront how their legacy environments need to evolve. “AI is pushing legacy also to become a younger metric as opposed to just being called legacy,” he says.
Integration itself becomes another significant consideration because AI solutions can touch multiple systems. Data flows need to be maintained, while the integrity and provenance of the information being consumed by models have to be understood. Change management then determines how the organisation can adapt as those systems evolve.
Why agentic AI changes the operating model
This is where Dutta sees agentic AI making a more fundamental difference. Rather than treating automation as the transformation of one isolated activity, he describes an environment in which multiple tasks within a process can be handled by agents, with other agents providing observability and humans remaining part of the control structure. “What agentic does is when you kind of pick up the leg of the process, then that process has got multiple tasks or activities,” he says.
The significance, in his view, is not simply that another task can be automated. It is that the organisation can begin to orchestrate processes differently, with agents performing activities, monitoring mechanisms observing them and humans stepping in when there is a deviation.
That is a significant departure from the earlier rule-driven automation model. Dutta points to RPA as an example of technology that could automate individual processes but lacked the intelligence component that AI now brings.
The result, he argues, should be a different target operating model rather than a collection of isolated AI implementations.
The five whys behind AI adoption
Dutta is particularly wary of organisations adopting AI simply because others are doing so. He argues that the decision needs to survive repeated questioning. “You need to ask the five whys recursively, till the time it becomes very, very clear of why you’re getting into this space,” he says. “The answer cannot just be very simply that everyone else is doing.”
At Canara HSBC Life, that questioning ultimately brought the customer to the centre of the strategy, with simplicity emerging as a second defining idea. “When we asked ourselves why we were doing this, the answer was clear. We wanted to keep becoming simpler,” Dutta says.
The objective is to make the company, its products, interactions and turnaround times simpler and more responsive. That also explains why he is cautious about putting AI directly in front of customers simply as a technology feature. “Customers always ask this question, what’s in it for me,” he points out.
Guardrails before autonomy
The same caution extends to security and governance. Dutta sees AI as introducing new dimensions to an organisation’s risk profile, particularly because of the amount of data involved and the increasingly connected nature of the industry. “Security, governance continue to remain at the top of the agenda because what AI is also dealing with is a lot of data,” he says.
The response, he argues, has to include clear guardrails, an understanding of how models operate and the ability to identify and correct deviations quickly. The risk profile itself cannot be treated as static. “New risks definitely are there and more will emerge. How and what scale nobody knows,” Dutta avers.
That uncertainty is one reason he does not see complete autonomy as the immediate destination. Human oversight remains part of the operating model while organisations become more familiar with the technology and its risks. “We are not completely autonomous yet because we are trying to settle ourselves with the technology in a far better way,” he says.
For Dutta, guardrails are ultimately an architectural and governance question. They have to reflect the particular solution, data and models involved rather than being treated as a generic layer added after deployment.
Two years after his last conversation on the subject, Dutta’s account points to an AI strategy that is less interested in AI as spectacle and more concerned with the architecture, data, integration, governance and operating-model changes required to make it useful. At the centre of that thinking is a deceptively simple test, whether technology can make the customer experience simpler and more responsive.
