From paperwork to intelligence: How ART Housing Finance is reinventing home lending


In affordable housing finance, the real technology story is no longer the digitisation of paperwork. It is the digitisation of judgement. ART Housing Finance is using digital workflows, data aggregation, automation and AI to move routine verification and processing away from human teams, allowing people to concentrate increasingly on exceptions, risk decisions and customer relationships.
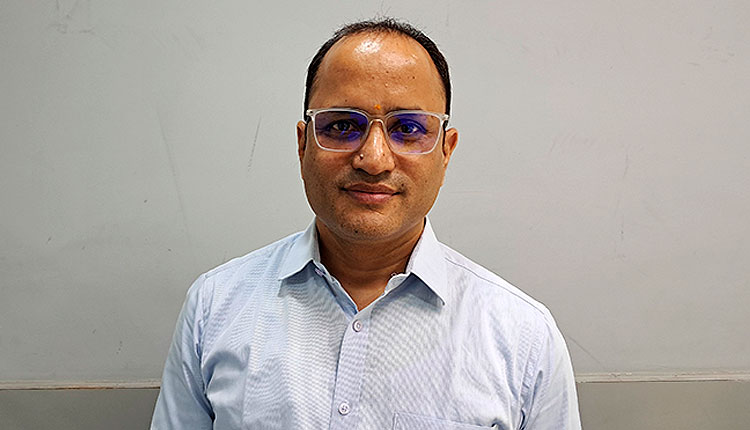
But for Anand Singh, CTO, ART Housing Finance, the objective is not technology for its own sake. It is to use technology to make lending more accessible, data-driven and productive while keeping humans in the loop where judgment matters.
The scale of the shift is already visible: digital sourcing, which Singh says was virtually zero two years ago, now accounts for 23% of the company’s business. Around 90% of customer KYC and onboarding is digitised, while roughly 80% of underwriting processes are automated or digitised.
The next phase is more ambitious: moving from automation towards agentic AI.
Turning a document-heavy business into a data-driven one
Housing finance has always been more complicated than simply checking a credit score. Lenders must establish a customer’s identity, understand income and repayment capacity, assess the property, verify ownership, and evaluate risks embedded in documents and financial behaviour.
Technology is progressively taking over the repetitive parts of that process. Account Aggregator data can help lenders understand cash flows. Digital property-title searches can map ownership histories. Intelligent document processing can extract information that once required manual scrutiny. Even property valuation is increasingly supported by historical and location-level data before physical verification takes place.
For affordable housing finance, this has a particularly important implication. Many customers operate with informal or non-standard income profiles, making traditional documentation an incomplete representation of their financial capacity.
Singh gives the example of a small business owner whose formal income may not tell the whole story. Analysing 12 or 24 months of bank transactions can reveal business cash flows, rental income, recurring expenses and other patterns that may otherwise remain invisible to the lender.
The result is not simply faster underwriting. It is potentially better-informed underwriting.
Technology, Singh argues, can also change the nature of human expertise. Instead of deploying highly experienced lawyers for routine property checks everywhere, technology can allow junior professionals to conduct basic due diligence, while experienced lawyers focus on identifying complex loopholes and strengthening the system.
That is a recurring theme in ART’s technology strategy: AI is intended to augment expertise rather than eliminate it.
The “home loan from home” proposition
The customer experience is another area where the technology architecture is becoming visible.
ART’s vision is what Singh calls “home loan from home.” A prospective borrower should be able to establish eligibility for a property from home through a conversational workflow. Singh says the current experience can provide an indicative assessment within five to seven minutes, subject to physical verification.
The same philosophy extends beyond origination.
Customers can use digital channels to access account statements, interest certificates, EMI information and repayment histories. Interestingly, the platform also enables customers to digitally initiate balance transfers—even when that means leaving ART for another lender. Singh describes this capability as something the company can “proudly” offer because it puts customer choice at the centre of the experience.
That is an unusual but revealing measure of digital maturity: making the customer journey transparent even when the outcome may not directly benefit the institution.
AI moves from the front door to the credit engine
ART’s AI journey is now moving beyond conversational interfaces.
Three AI agents have already been deployed across sales, customer service and collections. The sales agent helps qualify leads; the collections agent handles reminder and bounce calls as well as payment-link processing; and the customer-service agent supports routine interactions.
The larger opportunity, however, sits inside credit underwriting.
ART is developing an agentic underwriting model in which multiple agents work across the appraisal process. The system is intended to analyse documents, identify exceptions, assess policy fit and support risk-based pricing, allowing credit managers to concentrate on judgment and exceptional cases.
Singh expects pilots within three to five months, followed by deployment within roughly six to eight months, subject to successful pilots.
The strategic consequence could be significant. Instead of spending most of their time processing routine applications, credit professionals could spend more time designing policies for customer segments that are currently difficult to serve.
That could open another frontier for affordable housing finance: using AI not simply to reduce risk, but to understand risk that traditional models struggle to see.
Agentic AI—and the economics behind it
Singh’s approach to AI economics is deliberately measured.
ART does not deploy technology simply because it is available. The business first evaluates the use case, pilots it, and measures whether it improves productivity or efficiency. Ownership, he stresses, must sit with the business rather than being treated as an IT-only decision.
The company has even introduced a form of AI “rationing”. Singh describes a model in which a defined token budget is allocated to an AI process; once the threshold is reached, the workflow can revert to a manual process unless the business deliberately authorises additional AI usage.
That distinction matters. As AI moves into core financial processes, the question is no longer simply whether a model works. It is whether its business value, cost, governance, and risk justify scaling it.
From 23% digital business to 40%
ART’s technology transformation is already reflected in its operating ambitions.
Digital sourcing has moved from virtually zero to 23%, and Singh says the company is targeting 40% by the end of FY28, without a substantial increase in employee strength.
Payments are already 98% digitised, with only around 1.5–2% being made in cash. The entire last-mile collection calling process, Singh says, is automated. Customer self-service currently covers around 25% of processes, with a target of 60–65%, recognising that certain activities will continue to require human intervention.
The next target is even more consequential: ART wants 30% of its portfolio to eventually undergo automated underwriting without a human credit underwriter, using AI agents.
Technology as an organisational redesign
The deeper transformation, however, may be cultural.
ART has invested in AI literacy for its leadership, including workshops for CXOs and senior executives focused on practical use of AI tools. Singh’s rationale is straightforward: transformation must begin at the top.
The company is also using AI to automate mundane internal work—from expense processing and invoice routing to reconciliation and reminders. The aim is not simply to remove tasks, but to release employees from repetitive processing so they can work on stronger processes, business growth and higher-value activities.
For Singh, therefore, the next two years have a clear technology agenda: AI-led workflow automation and security. As more autonomous agents enter lending processes, protecting customer data, complying with regulation, and maintaining appropriate guardrails become inseparable from the AI strategy.
The larger story at ART is consequently not about replacing people with algorithms. It is about redesigning where people add value.
In a business historically dependent on documents, field visits, and manual judgment, technology is beginning to create a different model—one where machines handle the volume and humans increasingly focus on the exceptions, decisions, and opportunities that matter most.
